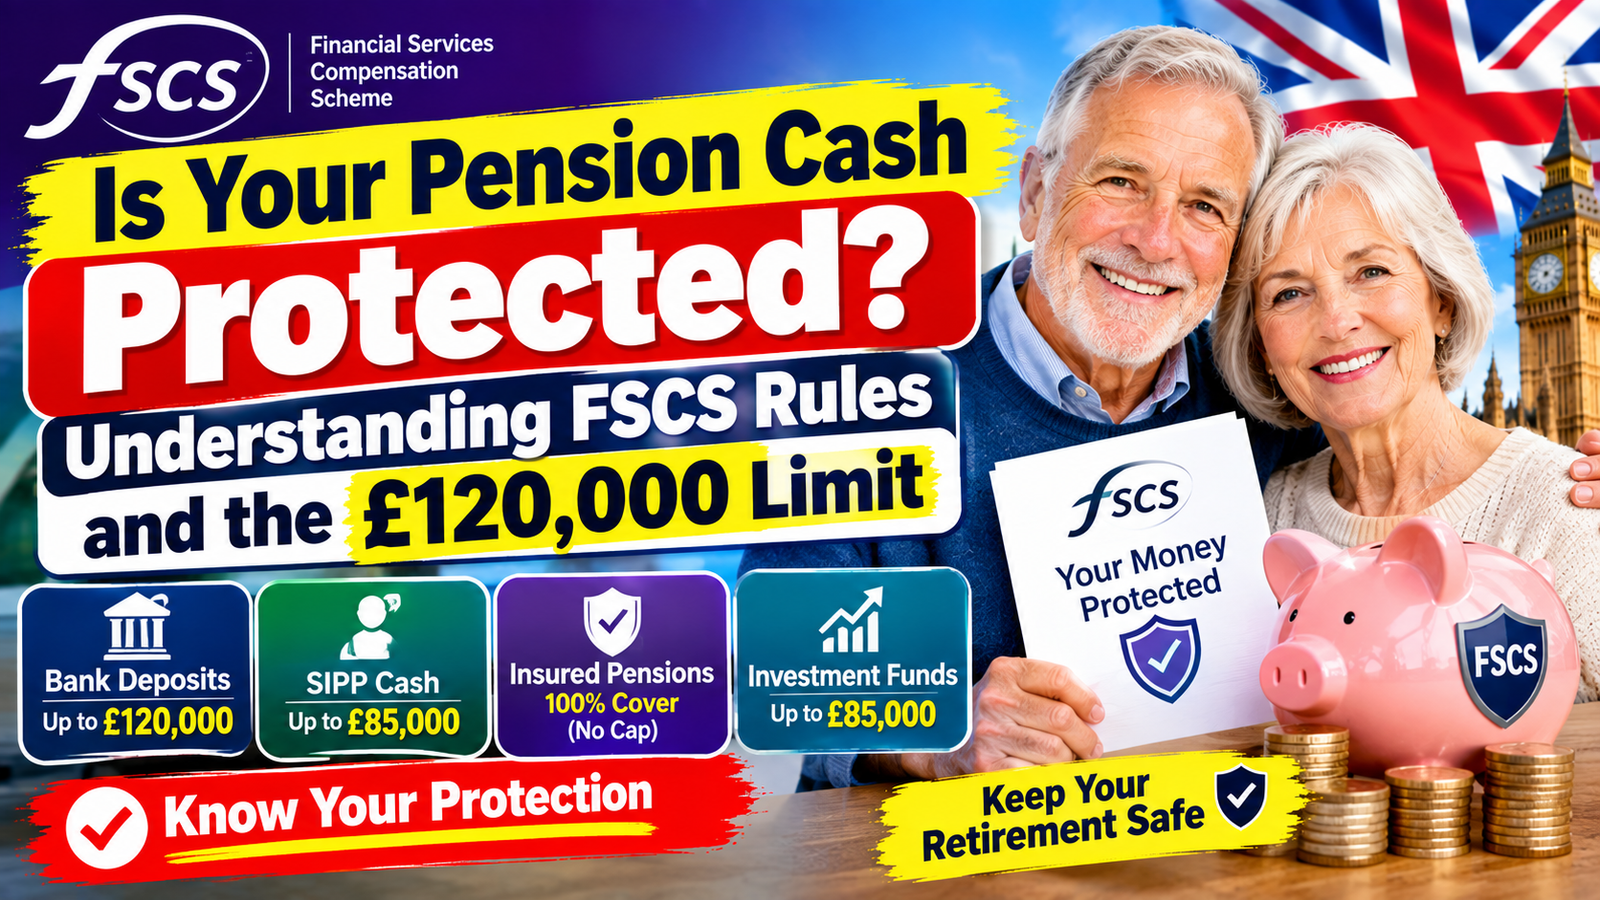
fscs pension cash protection : Hello Everyone, For many people approaching retirement, keeping part of a pension in cash can feel like a sensible way to reduce investment risk. Cash can provide flexibility for planned withdrawals and may help a saver avoid selling investments during a period of falling markets.
But holding cash inside or alongside a pension does not mean that every pound is automatically protected in the same way.
The Financial Services Compensation Scheme (FSCS) provides protection when eligible authorised financial firms fail, but the level of protection depends on what has failed and how the pension or cash arrangement is structured.
There is also an important change that pension savers need to know about: the FSCS deposit protection limit increased from £85,000 to £120,000 on 1 December 2025 for eligible deposits held with authorised banks, building societies and credit unions.
What Is FSCS Pension Cash Protection?
fscs pension cash protection is not one single rule that applies to every pension arrangement.
The FSCS has different protection categories for deposits, pensions, investments and insurance. As a result, the protection available to a pension saver can depend on whether the relevant failure involves a bank, a SIPP operator, a pension provider, an investment firm or another regulated business.
This distinction is particularly important for people who hold substantial amounts of uninvested cash within a SIPP.
The FSCS states that if a pension provider fails, eligible pension claims can normally receive 100% compensation with no upper limit where the arrangement qualifies as a contract of long-term insurance. By contrast, if a SIPP operator fails, FSCS protection is normally up to £85,000 per eligible person, per firm.
The £85,000 Figure Has Not Disappeared
The £85,000 figure is still relevant to some FSCS protection categories, which is why pension savers may continue to see it mentioned in official guidance.
However, it is no longer the standard FSCS deposit limit for ordinary bank savings.
From 1 December 2025, eligible deposits with UK-authorised banks, building societies and credit unions are protected up to £120,000 per eligible person, per authorised firm.
This is separate from the FSCS limit that can apply when a SIPP operator or investment firm fails.
Understanding that difference can prevent a saver from applying the wrong protection limit to their pension.
How Does FSCS Protection Work With a SIPP?
A Self-Invested Personal Pension, commonly known as a SIPP, can contain different types of assets.
These might include shares, funds, bonds and uninvested cash. The FSCS treatment can differ depending on the type of asset and the firm involved in the failure.
The FSCS says that where a SIPP operator fails and compensation is available, protection is normally up to £85,000 per eligible person, per firm. It also explains that investment failures involving an investment held within a personal pension may be eligible for compensation up to £85,000 per pension scheme member, subject to the relevant rules.
That does not mean every SIPP balance is simply insured up to £85,000 regardless of circumstances. The precise protection depends on the nature of the claim and which regulated firm has failed.
What If the Cash Is Actually a Bank Deposit?
This is where the distinction becomes particularly important.
If money is held as an eligible deposit with a UK-authorised bank, building society or credit union, the FSCS deposit protection limit is now £120,000 per eligible person, per authorised firm.
The FSCS says the limit applies across accounts held with the same authorised firm. If several banking brands operate under the same authorisation, the balances are generally treated together for the purpose of the protection limit.
Therefore, pension savers should not assume that using different brand names automatically creates separate £120,000 protection limits.
Why Banking Licences Matter
Imagine a saver has money with two different banking brands.
If those brands are actually operating under the same banking authorisation, the FSCS does not necessarily treat them as two completely separate institutions for compensation purposes.
The FSCS explains that where multiple brands share an authorisation, the £120,000 limit can apply to the combined eligible deposits held across those brands.
This is why checking the underlying authorised firm is more useful than simply looking at the name printed on a savings account.
The FSCS provides a protection checker that can help consumers identify whether different banks or brands share an authorisation.
What About Pension Providers?
Not every pension is structured like a SIPP.
The FSCS says many personal and stakeholder pensions provided by UK-regulated insurers can qualify as contracts of long-term insurance. Where the relevant FSCS conditions are met and the pension provider fails, compensation can be 100% of the claim with no upper limit.
This does not mean that the pension is protected against normal investment losses.
FSCS protection is designed to provide compensation following the failure of an eligible firm. It is not a guarantee that an investment will maintain its value.
For example, if an investment falls because financial markets decline, that ordinary investment loss is not automatically covered by FSCS.
What About Money Market Funds?
Some pension investors use money market funds or similar cash-like investments because they want lower volatility while keeping money invested.
However, a money market fund is not the same thing as an insured bank deposit.
The FSCS explains that investment protection can apply when an authorised investment firm fails and the relevant conditions are satisfied, generally up to £85,000 per eligible person, per firm. But FSCS does not compensate investors simply because an investment performs poorly or falls in value.
Therefore, calling every cash-like pension product “cash protected by FSCS” can be misleading.
Temporary High Balances
There is another important protection category for certain large deposits.
The FSCS says qualifying temporary high balances can receive protection of up to £1.4 million for up to six months following certain major life events. Examples can include proceeds from selling a home or receiving an inheritance.
This should not be interpreted as automatic extra protection for every large pension withdrawal.
Whether a particular balance qualifies depends on the rules governing temporary high balances and the circumstances that created the deposit.
Anyone moving a substantial pension lump sum into a bank account should therefore check the current FSCS rules rather than assuming the whole amount will receive temporary high-balance protection.
What Happens When You Take Pension Cash?
Pension access rules are a separate issue from FSCS protection.
Under current UK tax rules, people can usually take up to 25% of their pension as a tax-free lump sum, subject to the applicable limits and individual circumstances. GOV.UK currently states that the standard maximum tax-free lump sum is £268,275, although protected allowances can change the amount available to some people.
The normal minimum pension age is currently 55 and is scheduled to increase to 57 from 6 April 2028, subject to the relevant rules and exceptions.
Once pension money is withdrawn and placed into an ordinary bank account, it is no longer simply protected according to the rules of the pension arrangement. The applicable deposit protection rules can become relevant instead.
This is why retirement planning should consider both pension protection and bank deposit protection.
How Can Pension Savers Check Their Protection?
The first step is to identify exactly where the money is held.
A pension statement may show the pension provider or platform, but that does not always tell you which underlying institution holds uninvested cash.
Ask the provider what happens to cash that is not invested and whether it is held as a bank deposit, invested in a cash-like fund or handled through another structure.
You should also establish which authorised firm is responsible for the relevant money.
For ordinary bank deposits, the FSCS provides an online protection checker that uses information from the Financial Conduct Authority’s Financial Services Register.
For a SIPP, it is sensible to ask the provider specifically which FSCS protection category applies if the SIPP operator fails and which protection may apply if an underlying bank holding client cash fails.
Should Large Cash Balances Be Spread Across Banks?
For eligible bank deposits, spreading money between separately authorised deposit-taking firms can increase the amount that falls within the £120,000 protection limit.
For example, a person with £240,000 of eligible savings could potentially have £120,000 protected at one authorised firm and another £120,000 at a separate authorised firm, subject to the detailed FSCS rules.
However, simply using two different banking brands does not necessarily achieve this if both brands share the same authorisation.
For pension cash, the position can be more complicated because the pension structure and the identity of the failed firm matter.
What Pension Savers Should Not Assume
There are several common misconceptions worth avoiding.
First, the old £85,000 deposit limit is no longer the current standard deposit limit. It was replaced by £120,000 from 1 December 2025.
Second, the £120,000 deposit limit should not automatically be applied to every pension or investment product.
Third, FSCS protection does not protect against ordinary investment market losses.
Finally, having several accounts with different brand names does not necessarily provide several separate protection limits if the brands share the same authorised firm.
Final Thoughts
Keeping some pension money in cash can play an important role in retirement planning, but savers should understand exactly what type of protection applies.
The key point in fscs pension cash protection is that different types of financial failure can trigger different FSCS rules.
For eligible bank deposits, the current FSCS protection limit is £120,000 per eligible person, per authorised firm, following the increase that took effect on 1 December 2025. For SIPP operator failures, the FSCS normally provides up to £85,000 per eligible person, per firm, while qualifying insured pension arrangements can receive 100% protection with no upper limit when the relevant conditions are met.
The safest approach is therefore not to rely on one headline figure. Check your pension structure, identify where your cash is actually held and confirm which authorised firm would be responsible if something went wrong.
For significant retirement savings, understanding these details can be just as important as deciding how much money to keep in cash in the first place.